
If you inherited a Closely Held LLC held within an IRA, you may have several options available depending on your beneficiary status and goals. This guide explains how the inheritance process works, your available options, and the documentation required for each option.
A Closely Held LLC held by an IRA is commonly referred to as a Checkbook IRA. In this structure, the IRA owns the LLC, and the LLC may hold assets such as real estate, notes, private investments, or cash.
Your First-Step Checklist
Required actions
- Open an IRA with NDTCO.
- Complete the Inherited IRA Election Form (IEF)
- Provide a copy of the Death Certificate.
- Review your inheritance, its structure, options, and any co-beneficiary requirements
Open your account and review the records
Opening an account allows NDTCO to communicate with you securely and facilitate the transfer of inherited assets. The Inherited IRA Election Form identifies your beneficiary type and authorizes the internal transfer of assets to your account.
- Open the account appropriate for your beneficiary status.
- Complete the Inherited IRA Election Form and supply the death certificate. The election form records your instructions for NDTCO’s beneficiary processing.
- Review the original owner’s IRA statement and the purchase or ownership documents NDTCO has available. If you need information about LLC management, outstanding obligations, or the underlying investments, you may need records from the LLC, its manager, or a legal professional.
- Tell the Life Events Team if other beneficiaries are involved or if you lack essential LLC documents.
IMPORTANT | What NDTCO can and cannot do
NDTCO can explain its custodial paperwork and account-processing requirements. NDTCO does not manage the LLC, value or endorse its investments, decide how an LLC should be operated, or provide tax, legal, or investment advice.
Understand What You’ve Inherited
An IRA may own membership interest in a closely held LLC. The LLC, in turn, may own investments such as real estate, private notes, cash, or other property. Some IRA-owned LLC structures are described as “checkbook IRAs,” but not every closely held LLC is a checkbook-control arrangement.
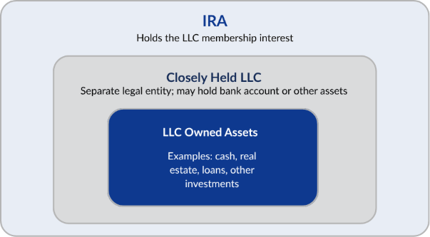
The diagram shows a possible structure, not necessarily your specific LLC. The IRA’s membership interest and the assets titled to the LLC are distinct and have been selected by the decedent. A change in IRA ownership does not necessarily transfer the ownership of every asset held by the LLC.
Review your options.
The options below describe the different ways an inherited IRA-owned LLC may be handled. Some options, such as liquidation, may not be available.
|
Option |
What changes |
Items to consider |
|
Keep the LLC in your IRA |
Ownership is re-assigned into the proper beneficiary or spousal IRA |
LLC operating documents, ownership assignment, co-beneficiary interests, ongoing IRA rules |
|
Distribute the LLC (in-kind) |
Distribute the membership interest out of the IRA into personal ownership |
Valuation requirements, tax reporting, legal ownership documentation, and potential taxes |
|
Liquidate the LLC |
Sell LLC-owned assets or arrange an appropriate wind-down; manage cash or remaining ownership under LLC and IRA rules |
Manager authority, liabilities, legal dissolution (if applicable), ownership transfers, sale proceeds |
The Steps for Your Selected Option
Depending on your circumstances, you may choose one of the following options:
Option 1: Keep the LLC membership interest in an IRA
This option allows the inherited investment to remain in an IRA arrangement, subject to the applicable beneficiary rules. A transfer to another custodian may be possible IF that custodian accepts the asset and the transfer qualifies under the inherited IRA requirements.
Your steps:
- Obtain and prepare any LLC membership-interest assignment or other ownership documents required under the LLC operating agreement and NDTCO procedures.
- Complete any beneficiary allocation requirements, if multiple beneficiaries share the interest.
- Submit completed documents to NDTCO.
NDTCO’s role: We will review documentation, execute the documents when authorized, and record the internal transfer after applicable requirements are met. If multiple beneficiaries are inheriting the same asset, NDTCO processes all internal transfers from the decedent account on the same day. As a result, all beneficiaries must complete their required paperwork before assets can be transferred. Once all requirements have been satisfied, the ownership interest will be transferred to the beneficiaries' IRA accounts.
After the transfer: You’ll need to continue meeting the LLC’s legal obligations and the inherited IRA’s valuation and distribution requirements. If you plan to transfer to another custodian, ask about acceptance and valuation requirements before initiating the transfer.
Option 2: Take an in-kind distribution of the LLC interest
An in-kind distribution moves an asset rather than cash out of an IRA, and into personal possession. NDTCO generally reports IRA distributions on Form 1099-R; its tax implications depend on the applicable IRA and tax rules.
Your steps:
- Prepare any required re-titling documents
- Obtain a current Fair Market Valuation (FMV) if the most recent valuation is more than 12 months old.
- Submit the valuation and supporting documents to NDTCO.
- Complete our Distribution and Withholding form under Settings in your NDTCO account
- Follow the approval instructions provided by NDTCO.
NDTCO’s role: We will review and sign required documents. Execute where applicable. Process the approved distribution, and complete required reporting.
Please refer to the NDTCO Fee Schedule for applicable distribution fees. For more information regarding valuations and supporting documentations, please visit Fair Market Valuations.
IMPORTANT | Tax consideration
An inherited IRA distribution can be taxable even when you receive an LLC interest instead of cash. Tax treatment differs for traditional and Roth IRAs. Distributions following death generally are not subject to the 10% early-distribution additional tax, subject to relevant exceptions and later spouse elections. Consult a qualified tax professional.
Option 3: Liquidate the LLC
Selling an investment owned by the LLC, paying money from the LLC to its IRA member, and formally dissolving the LLC are separate actions. The correct chain of events depends on the LLC’s operating agreement, ownership, obligations, and nature of the investments.
Your steps:
- Confirm who has the authority to act for the LLC and review its operating agreement, obligations, and assets.
- Coordinate any sales or liquidations of LLC-held investments through the person authorized to act for the LLC.
- Retain sale and banking documents and deposit all proceeds into the LLC bank account.
- Complete the Sell Asset Form in your NDTCO account.
- Arrange to have funds from the LLC sent to the decedent account.
NDTCO’s role: We will sign any required documents on behalf of the IRA. We do not sell any LLC-owned assets or dissolve the LLC on a beneficiary’s behalf.
After processing, funds held in an inherited IRA may be retained in cash, invested in other assets at the beneficiary’s direction, transferred to another custodian, or distributed. Fees and tax consequences depend on the transaction. Please refer to the NDTCO Fee Schedule for applicable fees.
Important
- All cash held by the LLC must first be returned to the IRA.
- Applicable fees must be paid before assets are transferred.
If There Are Multiple Beneficiaries
When multiple beneficiaries inherit the same LLC, the ownership interest must be divided according to the beneficiary designation. A closely held LLC interest may require additional documentation before it can be allocated among beneficiary accounts.
In some cases, the asset held in the account does not divide evenly. When this happens:
- All beneficiaries must agree on how the interest will be allocated
- A written allocation agreement will be required
- All beneficiaries must sign the agreement before a notary public.
NDTCO will provide guidance if this step becomes necessary.
Important rules
Keep IRA and personal assets separate
Do not personally use LLC money or property while interest remains IRA-owned. Improper transactions between the IRA, its assets, and disqualified persons can result in serious tax consequences. An IRA beneficiary’s role does not automatically grant LLC management or bank-signing authority.
Handle LLC income according to ownership and entity requirements
Cash or assets owned by the LLC are part of the IRA and may not be transferred directly to the IRA account owner or other parties. Rent, interest, dividends, and other payments earned from LLC-owned investments may be received by the LLC according to its arrangements. Payments by the LLC to its member(s); and distributions from the IRA to you, are different transactions.
Maintain a fair market valuation
Privately held LLC interests often lack publicly available and observable market prices. The IRS requires custodians to report IRA values annually. To comply with IRS regulations, NDTCO requires annual valuations for all IRA-held LLCs. Valuations may also be required for ownership changes or distributions.
Understand inherited IRA distribution deadlines
Completing an LLC re-assignment does not satisfy an inherited IRA’s required minimum distribution requirements. The rules depend on the original owner’s date of death, whether distributions had begun, and other facts. Some inherited IRAs must be fully distributed within 10 years; annual withdrawals may also be required. Beneficiaries should review their individual deadlines with a tax professional.
Consider potential LLC tax filings
An IRA investment involving operating income or debt financed property may create unrelated business taxable income and associated filing or tax responsibilities. Consult a qualified professional familiar with IRA-owned entities.
For more details on these and other important topics, review IRS Rules and Regulations , and Checkbook IRA/LLC FAQs
Timing and staying in touch
Please notify NDTCO within 60 days of completing the Inherited IRA Election Form whether you intend to:
- Transfer the LLC to an IRA.
- Take an in-kind distribution of the LLC.
- Liquidate the LLC.
An NDTCO Life Events Specialist will assist you throughout the inheritance process, but beneficiary participation and communication are essential. We ask that you communicate with us regularly on the steps you have taken.
Please keep us informed of the steps you have completed and respond to requests for information promptly.
Inactive Accounts
Accounts with no activity or communication for six months may be considered not in Good Standing.
In certain circumstances, NDTCO may distribute the inherited asset based on the most recently reported value. Any resulting taxes remain the responsibility of the beneficiary.
Need Assistance? If you have questions about your inherited Closely Held LLC or need assistance determining how you would like to proceed, please contact the NDTCO Life Events Team through the secure messaging center in your client portal.
Re-Titling Requirements
The beneficiary is responsible for preparing any documents necessary to re-title or re-assign the LLC ownership interest.
If You Are a Spousal Beneficiary Taking Ownership of the IRA
Use:
NDTCO, as Custodian, FBO [Your Name] Traditional IRA
Or
NDTCO, as Custodian, FBO [Your Name] Roth IRA
If You Have Inherited an IRA
Use:
NDTCO, as Custodian, FBO (Your Name), Bene – [Decedent Name] dcdt Traditional IRA
Or
NDTCO, as Custodian, FBO (Your Name), Bene – [Decedent Name] dcdt Roth IRA
If You Are Taking a Personal Distribution
The ownership interest must be re-titled into your individual name.
Sources & further reading
Internal Revenue Service, “Retirement Topics — Beneficiary.” https://www.irs.gov/retirement-plans/plan-participant-employee/retirement-topics-beneficiary
Internal Revenue Service, Publication 590-B, “Distributions from Individual Retirement Arrangements (IRAs).” https://www.irs.gov/publications/p590b
Internal Revenue Service, “Instructions for Forms 1099-R and 5498 (2026).” https://www.irs.gov/instructions/i1099r
Internal Revenue Service, “Retirement Topics — Prohibited Transactions.” https://www.irs.gov/retirement-plans/plan-participant-employee/retirement-topics-prohibited-transactions
Internal Revenue Service, “Instructions for Form 990-T.” https://www.irs.gov/instructions/i990t